Your payslip explained! By Abimbola Abdur-rahman Lekki
Again, there is an important distinction:
nA deduction from your salary is not necessarily an additional tax.
nWhere the law recognises the deduction in determining chargeable income, it may reduce the amount of income on which your tax is calculated.
nEmployees should therefore check their payslips and relevant remittance records to ensure that deductions described as NHF are properly accounted for.
n4. Health Insurance Contributions
nQualifying contributions under the National Health Insurance Scheme and applicable health-insurance arrangements may also be relevant to an employee’s tax computation.
nThe NTA expressly recognises qualifying contributions under the National Health Insurance Scheme among eligible deductions.
nThis is another reason employees should not automatically assume:
n“Everything deducted from my salary makes me poorer.”
nSome deductions may provide a current or future financial benefit and may also receive tax recognition.
n5. What About NSITF?
nHere is another area where employees should pay attention.
nThe Nigeria Social Insurance Trust Fund (NSITF) contribution is generally an employer obligation, rather than a deduction from the employee’s salary.
nTherefore, if an employee sees a deduction described as NSITF on a payslip, it is reasonable to ask the employer or payroll department to explain the basis for that deduction.
nThis distinction matters because:
nAn employer’s statutory contribution should not automatically be converted into an employee’s deduction.
nEmployees should understand the difference between what their employer is required to pay on their behalf and what is lawfully deducted from their salary.
n6. Loan Repayments
nNow we enter the world of non-tax deductions.
nSuppose Chinedu obtained a staff loan from his employer.
nHis payslip may show:
nStaff Loan Repayment — N100,000
nThat is a deduction from his salary.
nBut it is not PAYE.
nIt is repayment of money he previously borrowed.
nThis distinction is crucial.
nA payslip may therefore contain deductions that have absolutely nothing to do with taxation.
n7. Cooperative Contributions
nMany Nigerian workers belong to cooperative societies.
nA monthly deduction may therefore appear as:
nCooperative — N20,000
nAgain, this is not PAYE.
nIt may represent the employee’s contribution to a cooperative society or savings scheme, subject to the relevant authorisation given by the employer.
nThe employee should know whether the deduction is mandatory, voluntary or based on an agreement.
n8. Union Dues
nWhere applicable and properly authorised, trade union dues may also appear on a payslip.
nAgain:
nUnion dues are not PAYE.
nThey are a separate deduction with a different legal and institutional basis.
n9. Salary Advances
nSometimes an employee receives part of his or her salary in advance.
nThe subsequent repayment may appear as:
nSalary Advance — N50,000
nThis reduces take-home pay but does not represent income tax.
n10. Insurance and Other Voluntary Deductions
nAn employee may authorise deductions for:
nlife insurance;
nhealth insurance;
nprofessional subscriptions;
nsavings schemes;
ncooperative investments;
nemployee welfare schemes;
ncharitable contributions; or
nother approved workplace programmes.
nThese deductions should not automatically be confused with statutory taxes.
nThe golden rule is to ask: “Why is this money being deducted, and where is it going?”
nStatutory Versus Non-Statutory Deductions
nLet’s make this very simple.
nDeduction
nWhat it generally represents
nPAYE
nPersonal income tax deducted through payroll
nEmployee pension contribution
nRetirement savings under applicable pension arrangements
nNHF
nHousing fund contribution where applicable
nQualifying health insurance/NHIS contribution
nHealth insurance contribution
nLoan repayment
nRepayment of money borrowed
nSalary advance
nRecovery of salary paid in advance
nCooperative contribution
nEmployee savings/investment arrangement
nUnion dues
nTrade union contribution where applicable
nInsurance contribution
nInsurance arrangement
nOther authorised deductions
nDepends on the employment arrangement
nThe crucial point is that the existence of a deduction on your payslip does not make it a tax deduction for PAYE purposes.
nTax treatment depends on what the law specifically allows.
nAn Important Tax Secret: Some Deductions Can Reduce Your Tax
nThis is perhaps the most important lesson for Nigerian workers.
nThe Nigeria Tax Act provides for certain eligible deductions when determining an individual’s chargeable income.
nThese include qualifying:
nNational Housing Fund contributions;
nNational Health Insurance Scheme contributions;
npension contributions;
ninterest on loans for developing an owner-occupied residential house;
ncertain life assurance premiums or deferred annuity payments; and
nrent relief of 20% of annual rent paid, subject to a maximum of N500,000 and the statutory conditions.
nBut there is an important distinction:
nRent relief is not the same thing as a monthly payslip deduction.
nYou do not necessarily see “Rent Relief” deducted from your salary every month.
nRather, it is a statutory deduction used in determining chargeable income, subject to the conditions and claim requirements under the NTA.
nThis is precisely why tax education matters.
nYour Payslip Is a Conversation With Your Employer
nImagine that your payslip shows:
nGross Earnings:N500,000
nPAYE: N35,000
nPension: N40,000
nCooperative: N20,000
nLoan Repayment: N50,000
nYour net salary will obviously be substantially lower than your gross salary.
nBut these deductions do not all mean the same thing.
nN35,000 may represent your tax liability.
nN40,000 may be retirement savings.
nN20,000 may be your cooperative contribution.
nN50,000 may be repayment of money you borrowed.
nIf you simply look at the final amount credited to your account, you miss the story.
nYour payslip tells that story.
nWhy Employees Should Check Their Payslips Every Month
nYour payslip can help you answer five important questions:
n1. Did I receive the salary I was supposed to receive?
n2. Was my PAYE correctly calculated?
n3. Were my pension and other statutory contributions correctly deducted and remitted?
n4. Did my employer make any deduction that I do not understand or did not authorise?
n5. Does my payslip accurately reflect my financial records?
n nRelated Stories
 General News
CELEBRATING TWO YEARS OF TRANSFORMATIONAL LEADERSHIP IN THE PRESIDENTIAL AMNESTY PROGRAMME
Tomorrow, 14TH March 2026, as we look forward to the second anniversary, we reflect on the remarkable two years since the Administrator of the Preside
 General News
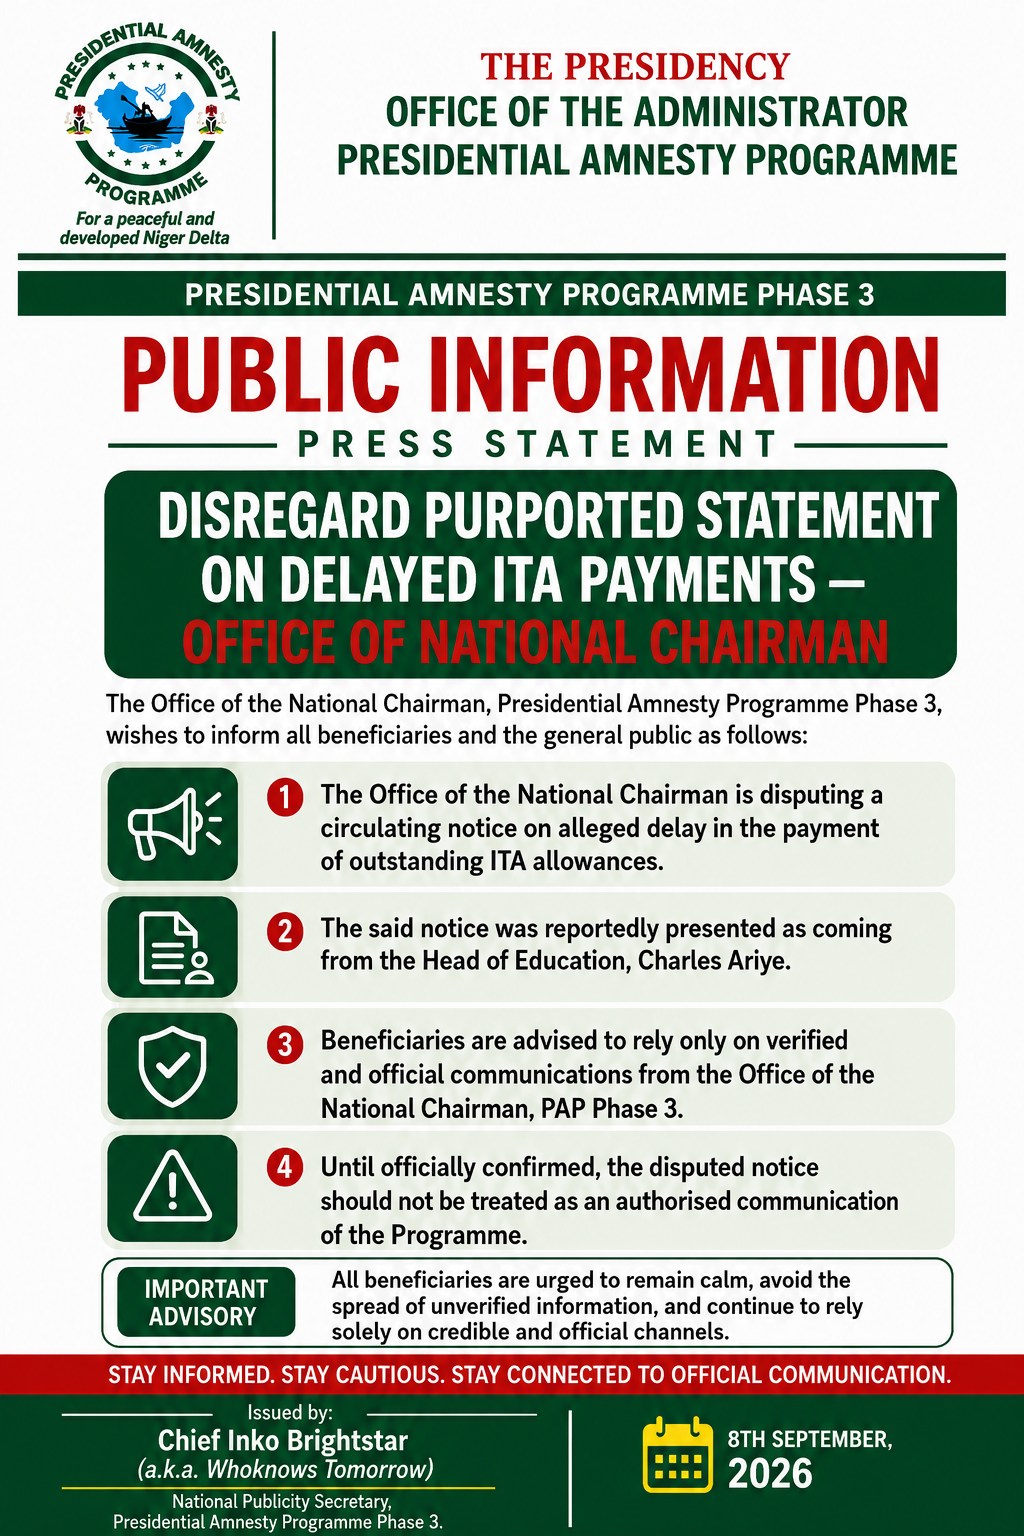
PRESIDENTIAL AMNESTY PROGRAMME PHASE 3: DISREGARD PURPORTED STATEMENT ON DELAYED ITA PAYMENTS — OFFICE OF NATIONAL CHAIRMAN
The Office of the National Chairman of the Presidential Amnesty Programme Phase 3, General Elaye ThankGod Dollar Slaboh, has called on beneficiaries a
 General News
RE: CLARIFICATION ON MY PERSONAL RELATIONSHIPS
PUBLIC NOTICErnrnRE: CLARIFICATION ON MY PERSONAL RELATIONSHIPSrnrnIt has become necessary to make this public clarification following the increasing