Transforming Nigerian Small Businesses: Leveraging Technology to Bring Aspirations to Life
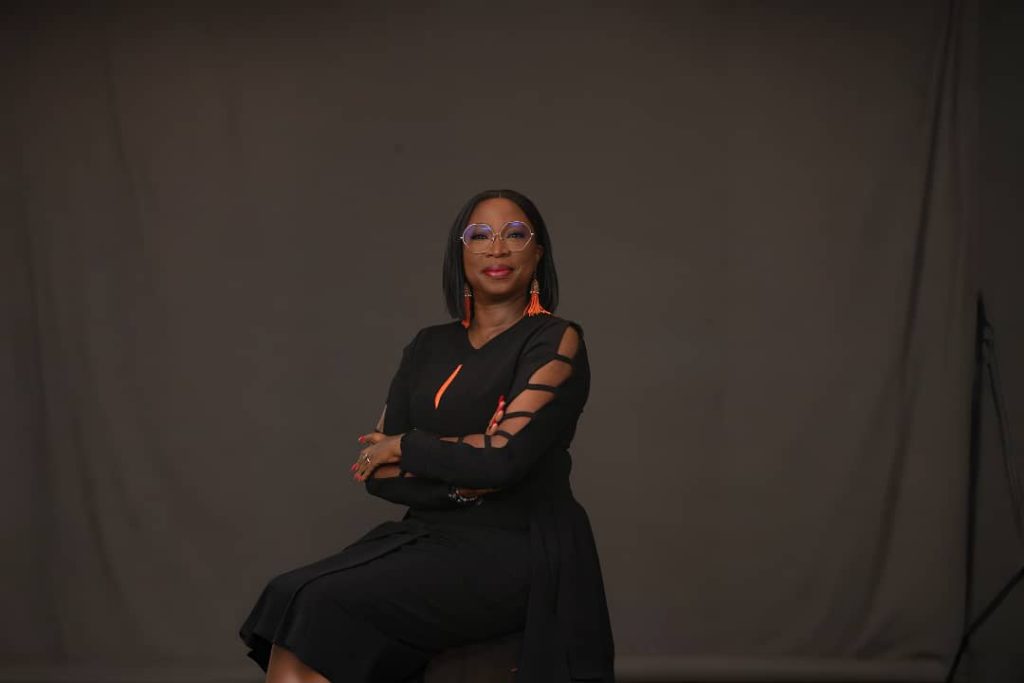
By Dr Folasade Femi-Lawal, country manager, West Africa, Mastercard
nAcross Africa, micro, small and medium-sized enterprises (MSMEs) are proving remarkably resilient and ambitious, growing and adapting even in a demanding economic climate. Nowhere is that energy more visible than in Nigeria.
nHome to nearly 40 million MSMEs, according to SMEDAN, these businesses are the backbone of the country’s economy, driving innovation, creating jobs and supporting livelihoods across communities.
nThese businesses have spent years building stability. Now they are building scale.
nMastercard’s newly released SME Confidence Index, a multi-market study spanning Africa and wider EEMEA region, captures that momentum. It found that 81% of Nigerian SMEs are optimistic about the next 12 months and 68% expect revenue growth. Most significantly, every business surveyed (100%) agreed that digital and online payments are critical to their future success.
nThe findings reveal more than optimism. They provide a clear blueprint for growth. Nigerian SMEs are investing in their people, embracing digital technologies, seeking access to capital and reaching beyond traditional boundaries to win new customers and markets.
nFor these businesses, digital payments are no longer just a ‘nice-to-have.’ They have become essential infrastructure that lasting growth depends on. However, a major bottleneck remains. While consumers are ready to pay digitally, a widespread ‘acceptance gap’ prevents merchants from receiving those payments. Bridging this divide requires moving beyond generic, off-the-shelf technology to build infrastructure that truly addresses local realities. And that is exactly where Mastercard is focused, reshaping the West African payment landscape so acceptance keeps pace with demand.
nEradicating the Hardware Barrier
nHistorically, the biggest barrier to digital inclusion for a local artisan or neighborhood retailer has been the cost of traditional Point-of-Sale (POS) hardware. If the cost of acceptance is higher than the merchant’s margin, the ecosystem stalls.
nOur strategy is pioneering ‘hardware-lite’ solutions that transform the smart devices merchants already own into secure payment hubs. We have seen the immediate impact of this through our ongoing regional deployments. For instance, through our collaborations with Wema Bank and UBA, we launched QR-on-Card solutions, an initiative that is actively enabling 1.8 million Nigerian SMEs and gig workers to accept payments instantly with zero hardware costs. This is not just a future goal. It is a tangible milestone in our mission to close the acceptance gap.
nBreaking Down Cross-Border Friction
nGrowth for Nigerian SMEs means looking beyond local borders to the broader African continent and the globe. Yet, according to the World Bank, Sub-Saharan Africa remains the most expensive region in the world for cross-border money movement, with transaction costs averaging nearly 8.5%. This friction stifles Pan-African trade.
nTo solve this, we need interoperable global rails. Through our Mastercard Move infrastructure, which connects over 200 countries and territories, we are helping businesses connect to new markets and move money across borders with greater speed and efficiency.
nWe are not building this in isolation. Through collaborations, with stakeholders such as Access Bank Group and Fidelity Bank, we are helping scale seamless cross-border remittances, while fintech companies like BMONI are enabling the instant issuance of virtual Naira and U.S. dollar cards. These innovations help address some of the payment and foreign exchange challenges that have historically limited access to global commerce and digital services.
nEmpowering through Capacity and Collaboration
nDeploying digital tools is only part of the equation. The Mastercard SME Confidence Index found that 79% of Nigerian SMEs view training and upskilling staff as one of their top priorities for growth, highlighting the importance of investing in people alongside technology.
nTruly scaling Nigeria’s economy requires a human-centered approach to digitization.
nThis is why technology investments must be paired with capability building.Through our collaboration with the Lagos State Employment Trust Fund (LSETF), we are driving financial literacy and digital onboarding for thousands of micro-merchants in Lagos State.
nBy investing in people alongside infrastructure, we can help ensure the digital economy is built on a foundation of equitable opportunity.
nTurning Transactions into Bankability and Trust
nOur 2026 SME Confirdence Index revealed that financial concerns remain a key challenge for entrepreneurs, with 69% actively seeking credit to fund their expansion.The research also found that 63% of SME owners currently use personal cards for business expenses, underscoring both the resourcefulness of Nigerian entrepreneurs and the need for greater access to financial solutions designed specifically for business growth.
nBy formalizing their operations through digital payments, SMEs generate a verifiable transaction history. This data helps build a stronger financial profile that lenders can use to assess creditworthiness and extend working capital.
nDigitalization therefore becomes more than an operational upgrade. It becomes a pathway to greater financial inclusion and business growth.
nBut as these businesses digitize, trust becomes increasingly important. Our research found that 60% of Nigerian SMEs view stronger physical and digital security as critical to supporting their growth. This concern is well founded. Mastercard’s inaugural Cyber Pulse Report found that financially motivated and disruptive activity accounts for 71% of observed cybercrime across EEMEA, highlighting why cyber resilience has become a business imperative rather than simply a technology consideration.
nTrust is the ultimate currency. To protect Nigeria’s growing digital economy, Mastercard has invested over $12.6 billion globally in cybersecurity and AI since 2019. As the Cyber Pulse Report highlights, strengthening digital resilience supports not only security, but also business continuity, operational resilience and long-term trust in the digital economy.
nPutting it All Together: The Story of a Modern Nigerian Entrepreneur
nWhat does this ecosystem look like in practice?
nImagine an independent beauty consultant who started her business entirely on social media. Previously, closing a sale required the friction of manual bank transfers. Today, she integrates a Pay by Link solution directly into her social media chats, allowing clients from Abuja to Port Harcourt to pay her instantly and securely.
nWhen she needs to pay for targeted ads or restock supplies from abroad, she relies on an instant virtual dollar card. And because her entire revenue stream is now digitized, she is building a financial profile that demonstrates her business performance and supports future growth opportunities.
nProtected by security technologies working behind the scenes, she is free to focus on what matters most: growing her brand and serving her customers.
nThis is the power of inclusive, digital-first infrastructure.
nThe Path Forward
nNigerian entrepreneurs already know what they need. Our SME Confidence Index shows them investing in their staff (79%), digitizing their operations (78%) and seeking capital to fuel expansion (69%). The ambition is clear. The question is whether the infrastructure can keep up.
nThat is our role. As technology providers, banks, fintech companies and policymakers, we build the rails beneath that ambition. That means low-cost acceptance, borderless payments and uncompromising security, delivered in step with local banks and fintechs. Get that right, and acceptance reaches every business that wants it.
nNigeria’s story is Africa’s story in miniature. Across the continent, entrepreneurs are ready to grow, innovate and compete on a bigger stage. Our job is to keep pace with their ambition, not ask them to wait for hours.
nBuild the infrastructure, and Africa’s entrepreneurs will do the rest.
n n nRelated Stories
 General News
CELEBRATING TWO YEARS OF TRANSFORMATIONAL LEADERSHIP IN THE PRESIDENTIAL AMNESTY PROGRAMME
Tomorrow, 14TH March 2026, as we look forward to the second anniversary, we reflect on the remarkable two years since the Administrator of the Preside
 General News
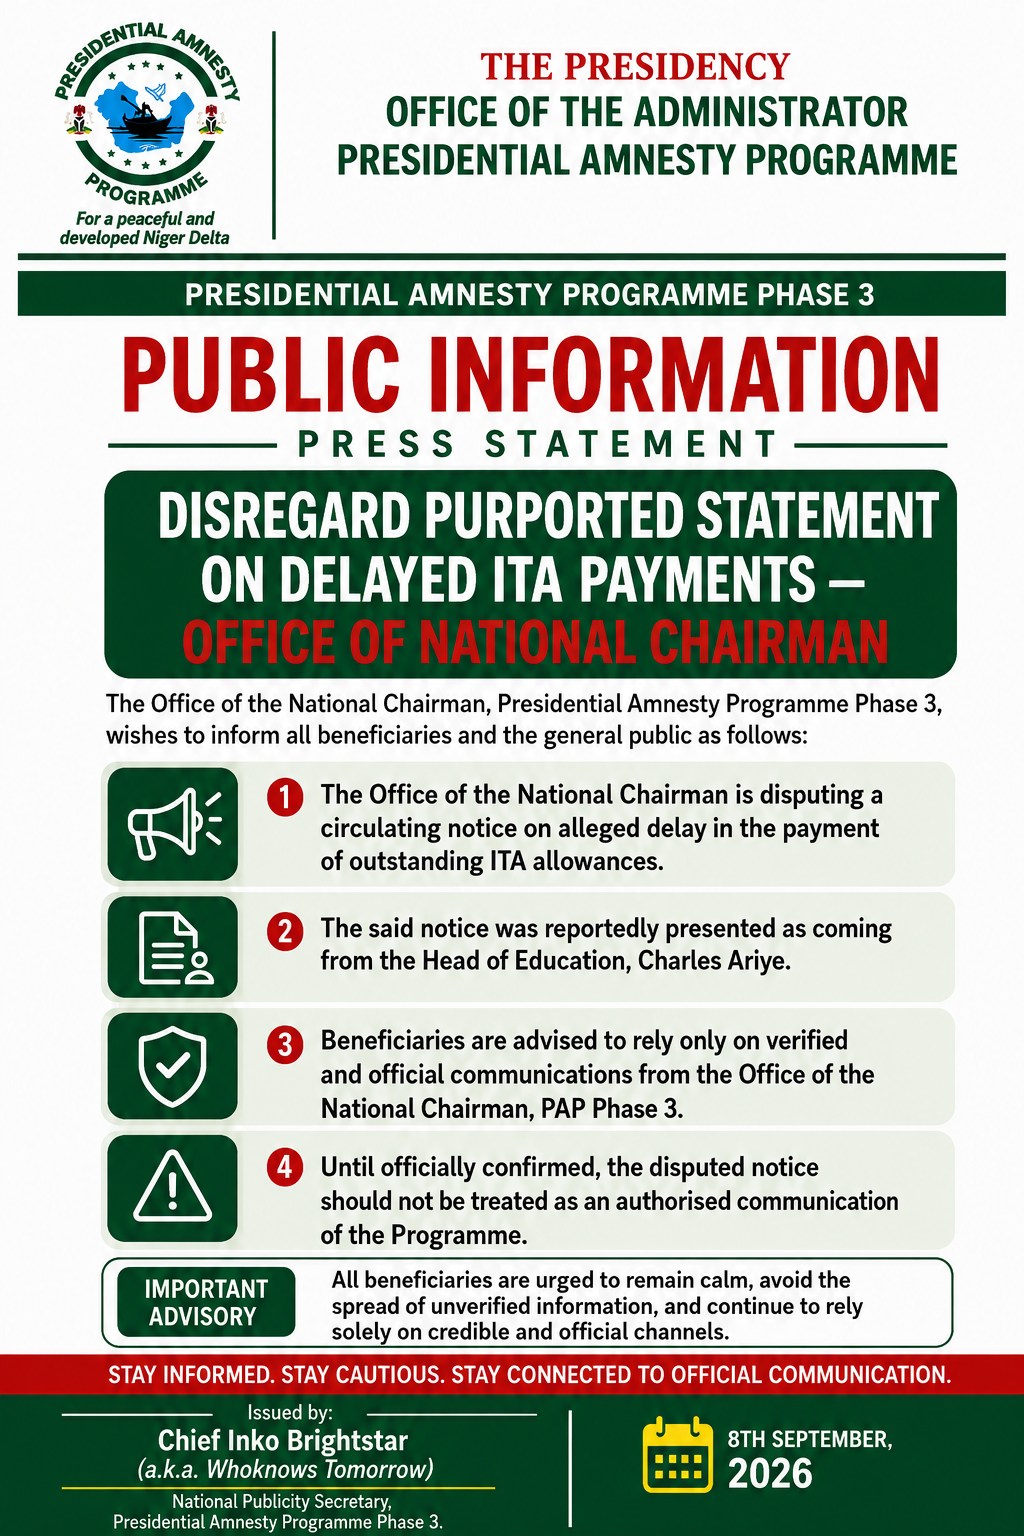
PRESIDENTIAL AMNESTY PROGRAMME PHASE 3: DISREGARD PURPORTED STATEMENT ON DELAYED ITA PAYMENTS — OFFICE OF NATIONAL CHAIRMAN
The Office of the National Chairman of the Presidential Amnesty Programme Phase 3, General Elaye ThankGod Dollar Slaboh, has called on beneficiaries a
 General News
RE: CLARIFICATION ON MY PERSONAL RELATIONSHIPS
PUBLIC NOTICErnrnRE: CLARIFICATION ON MY PERSONAL RELATIONSHIPSrnrnIt has become necessary to make this public clarification following the increasing