Financial institutions drastically reduce loans, withholding over N5.4 trillion from major industries
The Nigerian banking sector's lending landscape underwent a significant transformation in 2025, with Deposit Money Banks (DMBs) reducing their lending to key sectors such as oil and gas, and information and communication technology (ICT) by a substantial N5.45 trillion or 14.8 per cent year-on-year (YoY), largely due to the Central Bank of Nigeria's (CBN) withdrawal of regulatory forbearance and the subsequent loan portfolio clean-up.
nThis development was precipitated by the CBN's decision to end regulatory forbearance on troubled loans, which had been in place to prevent bank failures and widespread credit crunches during economic crises, with the total amount of money tied up in regulatory forbearance loans for seven major banks standing at $4.01 billion (over N6 trillion) as at the first quarter of 2025.
nThe affected sectors included Construction, Education, Manufacturing, Real Estate, and General Services, in addition to oil and gas and ICT, with the latest CBN data on Deposit Money Banks' Sectoral Distribution of Credit revealing a decline in credit to these eight sectors from N36.77 trillion in 2024 to N31.31 trillion in 2025.
nGeneral Services recorded the steepest decline, with credit falling by 25.02 per cent to N4.35 trillion from N5.80 trillion, representing a reduction of N1.45 trillion, while Manufacturing followed with a 22.52 per cent decline as credit dropped to N6.61 trillion from N8.53 trillion, translating to a contraction of N1.92 trillion.
nReal Estate also recorded a 17.2 per cent decline, with bank credit dropping to N792.71 billion from N957.38 billion, and credit to Oil and Gas (Services) fell by 12.35 per cent to N4.85 trillion from N5.53 trillion, while Oil and Gas (Industry) declined by 8.77 per cent to N10.59 trillion from N11.61 trillion.
nOther sectors that witnessed lower credit allocation include Information and Communication, where lending fell by 7.51 per cent to N1.76 trillion from N1.90 trillion, Education, which recorded a 5.73 per cent decline to N84.13 billion from N89.25 billion, and Construction, where credit dropped by three per cent to N2.29 trillion from N2.36 trillion.
nAccording to Tunde Abioye, Head of Equity Research at Quest Merchant Bank, the contraction in lending to certain sectors was primarily due to the CBN's decision to end regulatory forbearance on troubled loans, which resulted in sizable write-offs of loans by banks and a contraction in banks' and the industry's loan book.
nAbioye added that the most affected sectors were the oil and gas and manufacturing sectors, and that a likely implication is that banks will tighten their risk management frameworks and credit approval processes, with increased scrutiny of prospective loans.
nAyokunle Olubunmi, Head of Financial Institutions Ratings at Agusto & Co, corroborated this position, stating that the industry loan book was largely shaped by the write-offs associated with the forbearance termination, and that improved liquidity in the foreign exchange market moderated the demand for trade loans, which formed a significant proportion of the loans to the manufacturing sector.
nThe Manufacturers Association of Nigeria (MAN) argued that the sharp decline in manufacturing credit reflects deeper structural challenges confronting the sector beyond the recent loan clean-up by banks, with the association's Director-General, Segun Ajayi-Kadir, describing the 22.5 per cent contraction in manufacturing credit as disturbing.
nMAN warned that shrinking credit to manufacturing could reduce capacity utilisation, delay technology upgrades, trigger factory closures and job losses, while increasing Nigeria's dependence on imports and worsening supply-side inflation, and that inadequate financing could frustrate implementation of the Nigeria Industrial Policy and undermine efforts to diversify the economy away from oil.
nTo reverse the trend, MAN urged the CBN and the Federal Government to further reduce interest rates, lower the Cash Reserve Ratio (CRR) for banks supporting manufacturers, recapitalise the Bank of Industry, operationalise the N1 trillion Manufacturing Stabilisation Fund, and introduce government-backed credit guarantees to encourage lending to the real sector.
nDespite the decline in lending to several sectors, banks increased credit to agriculture, finance, and several others by N11.42 trillion during the period, with Agriculture recording a 26.4 per cent YoY increase to N3.61 trillion from N2.85 trillion, and Finance, Insurance, and Capital Market attracting N9.24 trillion from N7.75 trillion, representing a 19.29 per cent YoY increase.
nThe most dramatic expansion occurred in the "Others" category, where bank credit surged by 722.19 per cent YoY to N9.11 trillion from N1.11 trillion, accounting for N8.01 trillion or about 70 per cent of the total additional credit extended to the nine sectors that recorded growth.
nGovernment credit rose by 13.51 per cent YoY to N3.27 trillion from N2.88 trillion, while lending to Power and Energy (Industry) increased by 31.29 per cent YoY to N1.49 trillion, and Transportation and Storage also rose by 18.12 per cent YoY to N1.77 trillion.
nAbioye linked the rise in lending to finance and insurance to the prevailing high interest rate environment, stating that credit expansion to finance and insurance can be linked to the elevated market rates due to the CBN's tight monetary posture.
nLooking ahead, Olubunmi expressed optimism that lending will rebound this year, stating that with the conclusion of the portfolio clean-up exercise and the recapitalisation of the banks, a significant increase in exposure to the crucial sectors of the economy is anticipated in 2026.
nAbioye also expects banks to redirect lending to sectors with stronger growth prospects, including telecommunications and ICT, manufacturing, oil and gas, real estate, and construction.
Related Stories
 General News
CELEBRATING TWO YEARS OF TRANSFORMATIONAL LEADERSHIP IN THE PRESIDENTIAL AMNESTY PROGRAMME
Tomorrow, 14TH March 2026, as we look forward to the second anniversary, we reflect on the remarkable two years since the Administrator of the Preside
 General News
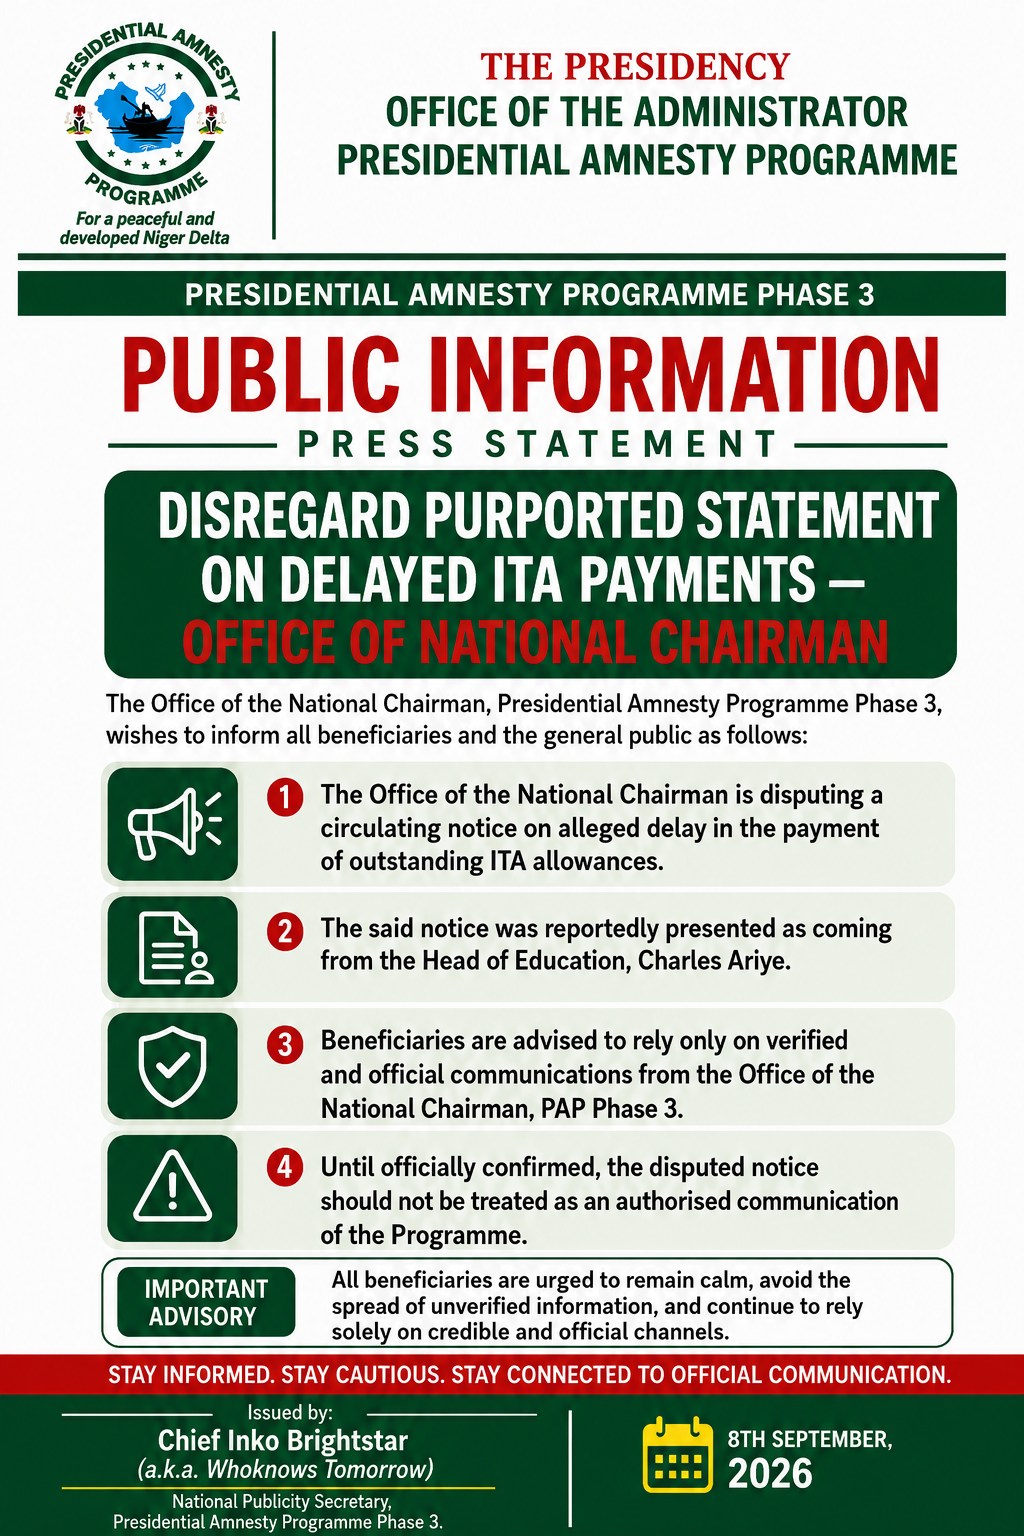
PRESIDENTIAL AMNESTY PROGRAMME PHASE 3: DISREGARD PURPORTED STATEMENT ON DELAYED ITA PAYMENTS — OFFICE OF NATIONAL CHAIRMAN
The Office of the National Chairman of the Presidential Amnesty Programme Phase 3, General Elaye ThankGod Dollar Slaboh, has called on beneficiaries a
 General News
RE: CLARIFICATION ON MY PERSONAL RELATIONSHIPS
PUBLIC NOTICErnrnRE: CLARIFICATION ON MY PERSONAL RELATIONSHIPSrnrnIt has become necessary to make this public clarification following the increasing