FG unveils loan for Nigerians to build or buy houses – How to apply

The Federal Government (FG), through the Federal Mortgage Bank of Nigeria (FMBN), offers loans to eligible Nigerians through the National Housing Fund (NHF) to help them buy, build, improve or renovate their homes.
nThe scheme provides eligible NHF contributors with mortgage financing of up to ₦50 million, at an interest rate of 6 per cent per annum, with a repayment period of up to 30 years.
nBut before applying, prospective borrowers need to understand who qualifies, how much they can receive and the steps involved.
nHow the FMBN mortgage works
nThe NHF Mortgage Loan is administered by FMBN through accredited and licensed Primary Mortgage Banks (PMBs).
nRather than applying directly to FMBN for the money, an applicant submits the mortgage application through an accredited mortgage institution.
nIf approved, the property being financed serves as security for the loan.
nThe scheme differs from many conventional mortgages because it offers eligible NHF contributors a concessionary interest rate and a repayment period of up to 30 years.
nHow much money can you get?
nFMBN’s current NHF Mortgage Loan information puts the maximum individual loan at ₦50 million.
nHowever, this does not mean every applicant will automatically receive the full amount.
nThe amount approved depends on factors including the applicant’s income, repayment capacity and the value or cost of the property.
nFMBN also states that an individual should generally not receive more than 90 per cent of the cost or value of the mortgaged property.
nSome older FMBN documents still contain a ₦15 million maximum loan figure. Applicants should therefore rely on the latest terms published by FMBN and those provided by an accredited mortgage institution.
nWhat does the loan cost?
nThe NHF Mortgage Loan is available to eligible contributors at an interest rate of not more than 6 per cent per annum.
nFMBN currently states that it provides the facility to accredited PMBs at 4 per cent, with the PMBs lending to NHF contributors at 6 per cent.
nYou can repay over 30 years
nOne of the major features of the scheme is the length of the repayment period.
nEligible borrowers can have up to 30 years to repay the mortgage, although the actual period depends on factors such as the borrower’s age, income and years in service.
nFMBN also assesses affordability, with repayment generally limited to a maximum of one-third of the applicant’s income.
nWho can apply?
nThe mortgage is not available to every Nigerian automatically.
nAn applicant generally needs to:
n- n
- Be a Nigerian citizen aged 18 or above. n
- Be registered under the National Housing Fund. n
- Have made continuous NHF contributions for at least six months. n
- Have a regular source of income. n
- Provide evidence of income if self-employed. n
- Apply through an FMBN-accredited and licensed mortgage institution. n
- Provide a property that satisfies the relevant legal and planning requirements. n
What can you use the money for?
nThe mortgage is specifically designed for housing purposes.
nAn approved borrower can use the facility to:
n- n
- Purchase a residential property. n
- Build a house. n
- Improve an existing home. n
- Renovate an existing home. n
What documents will you need?
nThe documents required can vary depending on the type of mortgage application.
nHowever, applicants may be asked to provide:
n- n
- NHF contribution records n
- Proof of income n
- Recent payslips or other income evidence n
- Property title documents n
- Property valuation report n
- Completed mortgage application form n
- Bill of quantities for construction n
- Employment and tax documents n
- Other legal documents requested by the mortgage institution n
How to apply
nThe application process begins with your NHF status.
nStep 1: Register and confirm your NHF contributions
nYou must be an NHF contributor and have made the required contributions for at least six months.
nFMBN also provides online services for NHF registration and account-related activities.
nStep 2: Find an accredited mortgage institution
nChoose an FMBN-accredited and licensed Primary Mortgage Bank or mortgage loan originator.
nThis institution will handle the mortgage application and guide you through the process.
nStep 3: Submit your application and documents
nComplete the required forms and submit your income, NHF and property documents through the mortgage institution.
nStep 4: Wait for assessment
nThe mortgage institution will assess your ability to repay the loan and examine the property and supporting documents.
nThe property will also undergo valuation and legal checks.
nStep 5: Approval and disbursement
nIf the application meets the relevant requirements and receives approval, the mortgage funds will be disbursed through the accredited mortgage institution for the approved housing purpose.
nWhere to apply
nNigerians interested in the scheme can find more information about eligibility, registration and the NHF Mortgage Loan through FMBN’s official website.
nApply/check the latest requirements: FMBN NHF Mortgage Loan
n nRelated Stories
 General News
CELEBRATING TWO YEARS OF TRANSFORMATIONAL LEADERSHIP IN THE PRESIDENTIAL AMNESTY PROGRAMME
Tomorrow, 14TH March 2026, as we look forward to the second anniversary, we reflect on the remarkable two years since the Administrator of the Preside
 General News
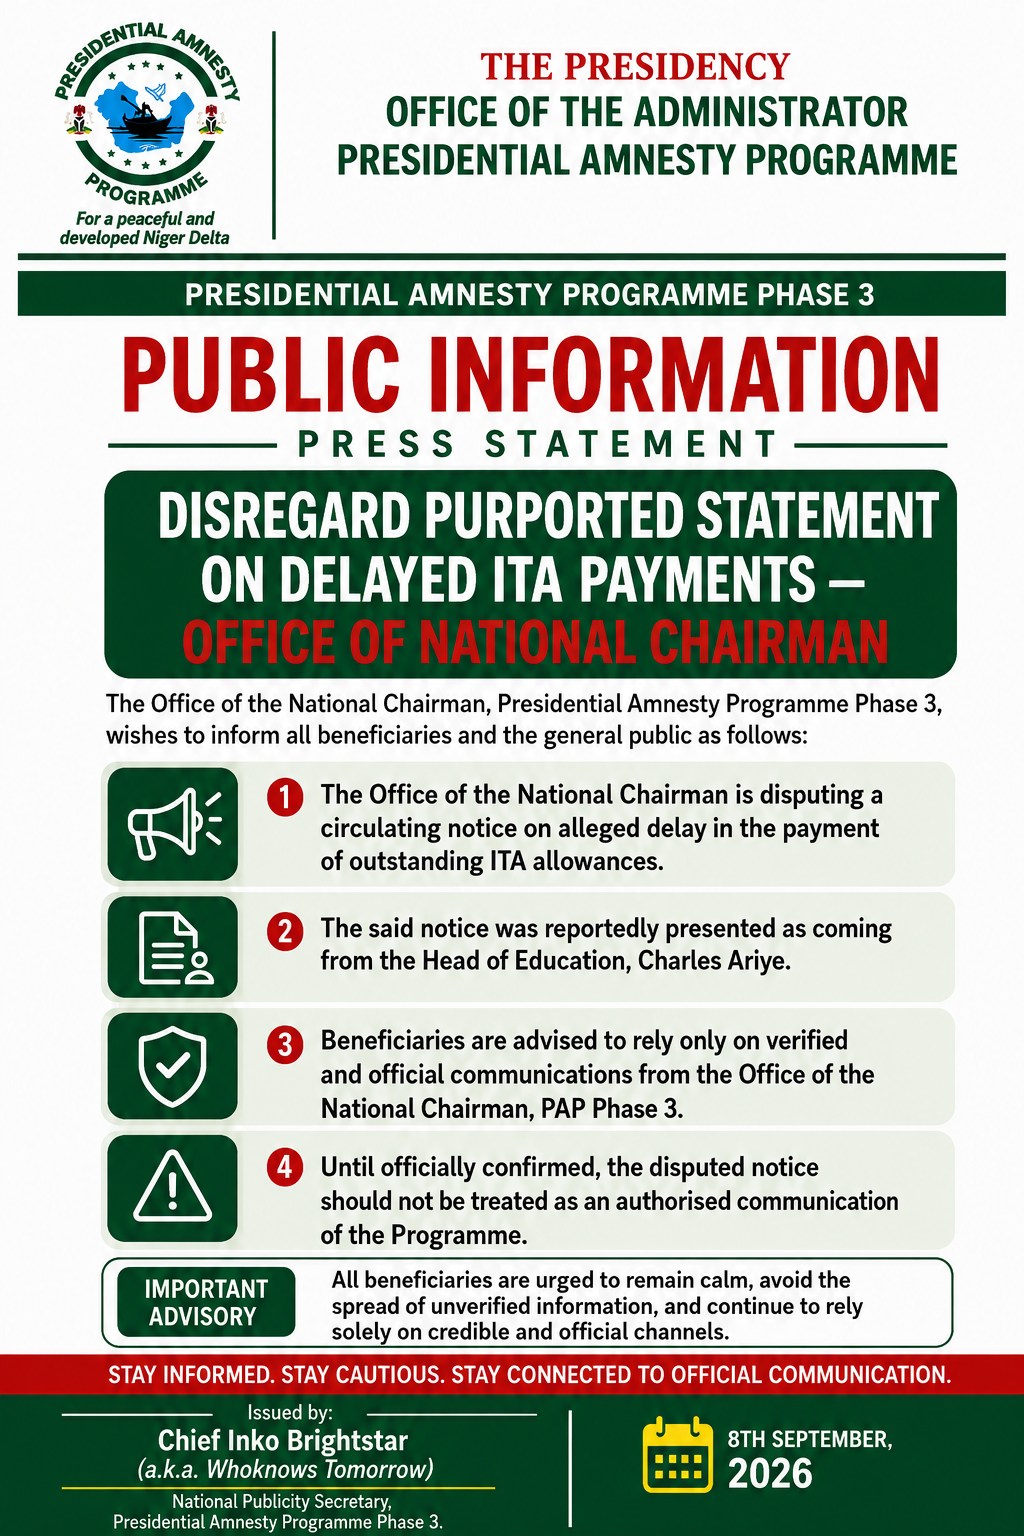
PRESIDENTIAL AMNESTY PROGRAMME PHASE 3: DISREGARD PURPORTED STATEMENT ON DELAYED ITA PAYMENTS — OFFICE OF NATIONAL CHAIRMAN
The Office of the National Chairman of the Presidential Amnesty Programme Phase 3, General Elaye ThankGod Dollar Slaboh, has called on beneficiaries a
 General News
RE: CLARIFICATION ON MY PERSONAL RELATIONSHIPS
PUBLIC NOTICErnrnRE: CLARIFICATION ON MY PERSONAL RELATIONSHIPSrnrnIt has become necessary to make this public clarification following the increasing