CBN warns banks, fintechs over cyber risks
…Says weak links could destabilise financial system
nBy Emma Ujah, Abuja Bureau Chief
nABUJA: The Central Bank of Nigeria, CBN, has urged banks, fintechs and other financial institutions to treat cybersecurity and third-party technology risks as critical financial stability issues, warning that vulnerabilities in one institution could trigger widespread disruption across the financial system.
nThe Director, Payments System Supervision at the CBN and Chairperson of the Nigeria Electronic Fraud Forum, NeFF, Dr Rakiya Yusuf, gave the warning at the 19th Annual Banking and Finance Conference of the Chartered Institute of Bankers of Nigeria, CIBN, in Abuja.
nSpeaking during a session titled, “Navigating Cyber and Systemic Risks in the AI-Driven Future of Banking: Implications for Financial Stability and Business Resilience,” Yusuf said the growing reliance of financial institutions on fintechs, payment service providers, cloud operators and other technology vendors had created new channels for cyber and systemic risks.
nShe warned that a weakness in a bank, fintech, payment service provider or technology vendor could spread rapidly across interconnected institutions, creating what she described as a “one-fire” effect capable of destabilising the entire financial system.
nYusuf said financial institutions must therefore move beyond securing their internal systems to strengthening safeguards across the wider financial ecosystem.
nShe urged banks and other operators to continuously assess their dependencies, third-party relationships and technology partners to determine how disruptions in one part of the ecosystem could affect their operations.
nThe CBN director stressed that operational resilience involved more than preventing cyberattacks, noting that institutions must also be able to maintain critical services during disruptions and recover quickly from incidents.
nShe disclosed that the CBN was strengthening its regulatory framework, supervisory processes and policy measures to identify and address vulnerabilities capable of threatening financial stability before they materialise.
nAccording to her, cyber and operational risk considerations were now being integrated into the product approval process to ensure that new financial products did not introduce systemic vulnerabilities.
nYusuf also urged financial institutions to extend cybersecurity and risk-management oversight to third-party service providers.
nShe said banks must assess the capacity of their technology partners to withstand and recover from cyberattacks and major operational failures.
nThe CBN director called for prompt reporting of cyber incidents and vulnerabilities to regulators, saying early disclosure would enable timely intervention before isolated breaches escalated into systemic threats.
nShe also advocated greater intelligence and information sharing among financial institutions, noting that stronger collaboration would improve the industry’s ability to detect emerging threats and coordinate responses.
nYusuf recommended the establishment of stronger Security Operations Centres, SOCs, capable of monitoring cyber threats across the financial ecosystem in real time.
nOn the growing adoption of artificial intelligence, she cautioned that innovation must be matched with accountability, insisting that automation should not eliminate human responsibility from financial decisions.
nShe described the approach as “automating accountability,” explaining that while AI could perform increasingly sophisticated tasks, human oversight must remain central to decisions affecting customers and the financial system.
nYusuf further urged financial institutions to strengthen data governance and pay greater attention to digital sovereignty by examining where critical data were stored, who had access to them, what intelligence could be derived from them and how such data influenced decision-making.
nShe warned that placing critical data or key technological capabilities beyond an institution’s effective control could expose the financial system to additional risks.
nYusuf maintained that safeguarding Nigeria’s financial system required a collective approach involving regulators, banks, fintechs, payment service providers and technology companies.
nShe said the objective should be to build a resilient ecosystem capable of absorbing shocks, containing cyber incidents and recovering swiftly without allowing the failure of one institution to threaten the stability of the entire financial system.
n nRelated Stories
 General News
CELEBRATING TWO YEARS OF TRANSFORMATIONAL LEADERSHIP IN THE PRESIDENTIAL AMNESTY PROGRAMME
Tomorrow, 14TH March 2026, as we look forward to the second anniversary, we reflect on the remarkable two years since the Administrator of the Preside
 General News
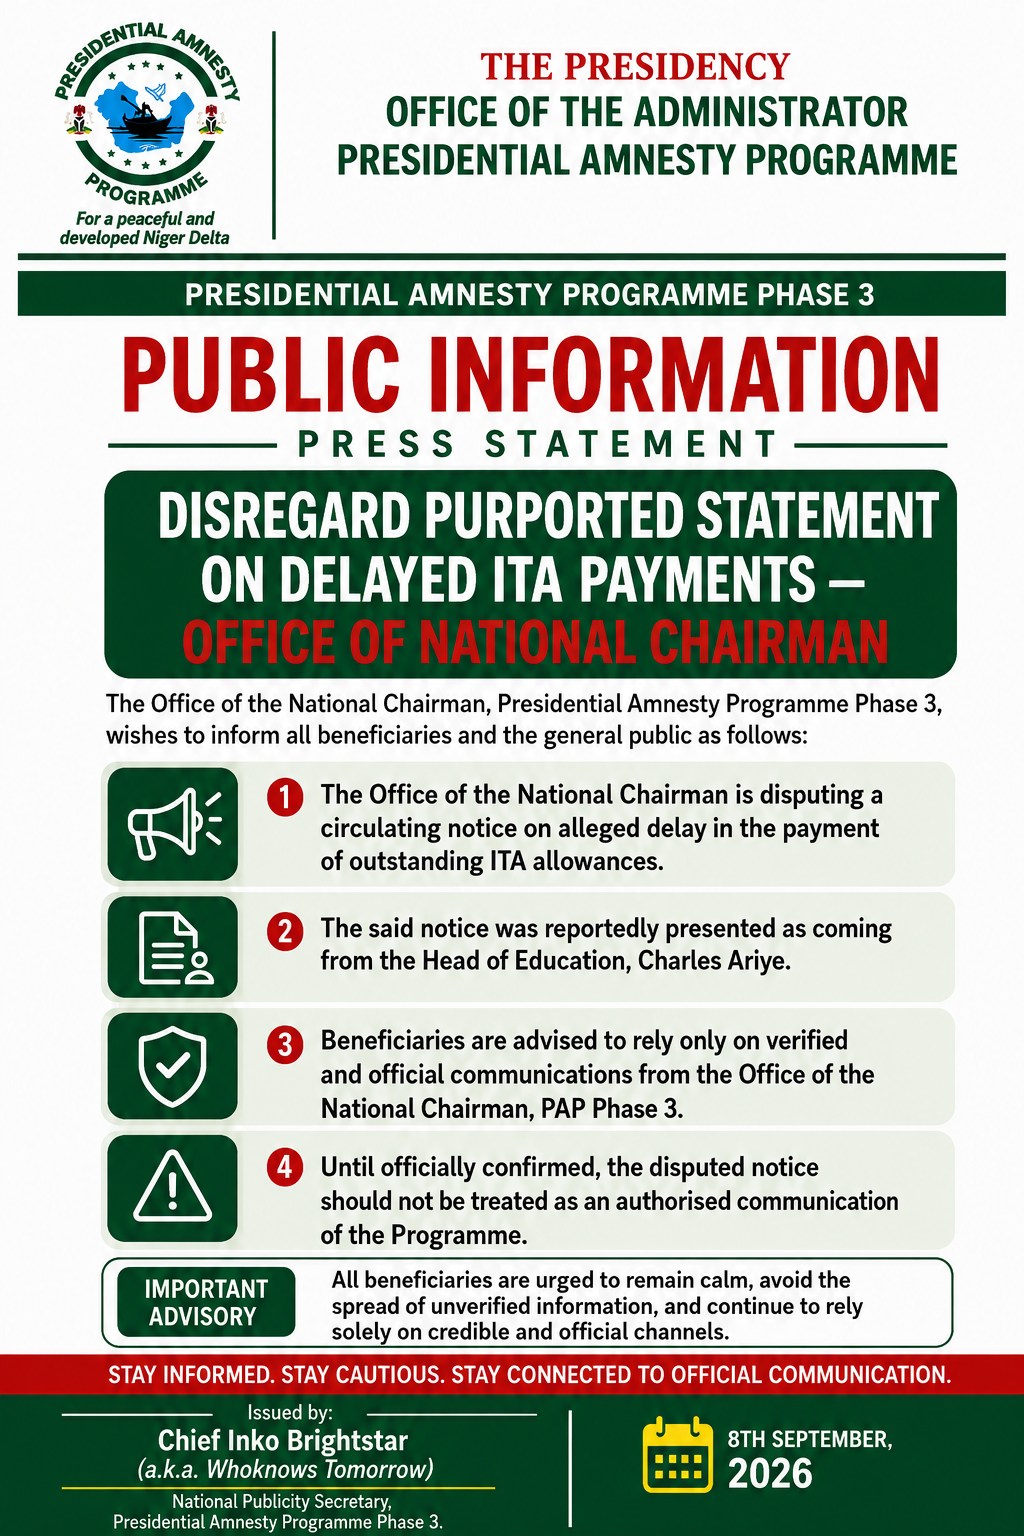
PRESIDENTIAL AMNESTY PROGRAMME PHASE 3: DISREGARD PURPORTED STATEMENT ON DELAYED ITA PAYMENTS — OFFICE OF NATIONAL CHAIRMAN
The Office of the National Chairman of the Presidential Amnesty Programme Phase 3, General Elaye ThankGod Dollar Slaboh, has called on beneficiaries a
 General News
RE: CLARIFICATION ON MY PERSONAL RELATIONSHIPS
PUBLIC NOTICErnrnRE: CLARIFICATION ON MY PERSONAL RELATIONSHIPSrnrnIt has become necessary to make this public clarification following the increasing