22 firms on NGX face debt exposure of N21.3trn
By Peter Egwuatu
nAbout 22 companies listed on the Nigerian Exchange Limited, NGX, are carrying varying levels of debt, totalling N21.3 trillion in the second quarter of 2026, as they seek to finance their operations and generate profits.
nOf the 22 companies, 11 are operating with debt-to-equity ratios above 2.0, highlighting varying degrees of reliance on borrowed funds to finance their businesses and raising concerns about the potential impact of interest costs, cash-flow pressures and shareholder returns.
nThe 22 companies are VFD Group, United Capital, UACN, TotalEnergies Marketing Nigeria, Tantalizers, SCOA Nigeria, Nestlé Nigeria, Neimeth International Pharmaceuticals, MTN Nigeria and Mecure Industries. Others are Infinity Trust Mortgage Bank, FTN Cocoa Processors, Ecobank Transnational Incorporated, Dangote Sugar, Conoil, C&I Leasing, BUA Cement, Aradel Holdings, AIICO Insurance, Access Holdings, Abbey Bank and Fortis Global Insurance.
nDebt-to-equity ratio above 2.0
nAn analysis of the data available to Vanguard shows that FTN Cocoa Processors has the highest debt-to-equity ratio at 28.61, followed by SCOA Nigeria at 14.37 and United Capital at 6.52.
nOther companies with ratios above 2.0 include Nestlé Nigeria, 5.74; Fortis Global Insurance, 4.66; UACN, 4.10; Neimeth International, 3.29; Mecure Industries, 3.0; MTN Nigeria, 2.98; VFD Group, 2.4; and Infinity Trust Mortgage Bank, 2.18.
nThe debt-to-equity ratio measures the extent to which a company relies on debt relative to shareholders’ equity. A ratio of 1.0, for example, indicates that debt is equivalent to equity, while a ratio of 2.0 indicates two naira of debt for every naira of equity.
nThere is, however, no single debt-to-equity ratio that can be regarded as normal for every company, according to analysts. Capital-intensive manufacturing, telecommunications and other sectors can operate with higher leverage, while excessive debt relative to equity can increase financial risk, particularly when interest rates are high or operating cash flows weaken.
nDebt value
nThe available data show significant differences in the capital structures of the companies. Total debt ranges from N9.31 billion for Tantalizers to N7.27 trillion for Access Holdings.
nEcobank Transnational Incorporated recorded total debt of N5.36 trillion, while MTN Nigeria had N2.78 trillion, Aradel Holdings N1.87 trillion and United Capital N1.22 trillion.
nOthers are BUA Cement, N663.34 billion; Dangote Sugar, N584.61 billion; Nestlé Nigeria, N445.11 billion; UACN, N308.78 billion; VFD Group, N252.17 billion; AIICO Insurance, N129.66 billion; Conoil, N72.05 billion; C&I Leasing, N71.67 billion; Mecure Industries, N66.17 billion; Fortis Global Insurance, N30 billion; and Infinity Trust Mortgage Bank, N27.16 billion.
nFTN Cocoa recorded N22.42 billion, Abbey Bank N20.37 billion, SCOA Nigeria N12.41 billion, Neimeth N9.33 billion and Tantalizers N9.31 billion.
nFTN Cocoa, SCOA stand out
nFTN Cocoa’s debt-to-equity ratio of 28.61 means that the company has N28.61 of debt for every N1 of shareholders’ equity. Its total debt is listed at N22.42 billion, while equity is shown at about N783.65 million.
nSCOA Nigeria also has a particularly high ratio of 14.37, although it has negative equity of N563.76 million. Negative shareholders’ equity is a separate warning sign because it means liabilities exceed the reported equity base.
nUnited Capital’s ratio of 6.52, alongside total debt of N1.22 trillion and equity of N187.09 billion, also points to substantial leverage.
nEquity value
nAccess Holdings recorded the highest equity value at N4.19 trillion, followed by Ecobank at N3.68 trillion, Aradel Holdings at N2.17 trillion, MTN Nigeria at N930.61 billion, BUA Cement at N659.13 billion, United Capital at N187.09 billion, Dangote Sugar at N170.36 billion, AIICO Insurance at N109.15 billion, VFD Group at N104.73 billion and Nestlé Nigeria at N77.56 billion.
nOthers are UACN, N75.71 billion; TotalEnergies Marketing Nigeria, N52.49 billion; C&I Leasing, N49.5 billion; Conoil, N44.39 billion; Mecure Industries, N22.02 billion; Infinity Trust Mortgage Bank, N12.47 billion; Abbey Bank, N10.88 billion; Fortis Global Insurance, N6.44 billion; Tantalizers, N4.76 billion; Neimeth, N2.84 billion; FTN Cocoa, N783.65 million; and SCOA Nigeria, negative N563.76 million.
nAnalysts’ comments
nCommenting on the implications for investors of the debt-to-equity ratios, Ambrose Omordion, Analyst and Chief Operating Officer at Investdata Consulting, said: “From an investor perspective, a high debt-to-equity ratio does not automatically mean that a company is in distress. Investors would need to examine the company’s earnings, cash flow, interest-cover ratio, maturity profile of its borrowings and the purpose for which the debt was raised.
n“However, high leverage can magnify both gains and losses. Where borrowed funds are deployed into profitable investments, debt can enhance returns to shareholders. Conversely, if earnings and cash flows weaken, a heavily indebted company may face difficulty meeting interest and principal obligations.
n“Investors may therefore pay particular attention to companies where high leverage is accompanied by weak profitability, negative shareholders’ funds or declining cash flows.
n“The figures from this data also show companies with considerably lower leverage. BUA Cement has a debt-to-equity ratio of 1.01, while Aradel Holdings is listed at 1.22, AIICO Insurance at 1.20, Conoil at 1.62, C&I Leasing at 1.50, and Ecobank Transnational Inc. at 1.50.”
nOn the implications for shareholders, he said: “For shareholders, rising leverage can increase the sensitivity of profits and dividends to interest rates and business conditions. Higher finance costs can reduce earnings available for distribution, while refinancing risks could become more pronounced when debt falls due.
n“At the corporate level, companies with manageable leverage can use debt to expand production, acquire assets and finance working capital without excessive dilution of existing shareholders’ ownership.”
nIn his remarks, Clifford Egbomeade, Economic Analyst and Communications Expert, said: “The data therefore suggests that debt levels should not be assessed in isolation. Investors need to consider the quality of earnings, cash-generation capacity, asset base, interest obligations and the sector in which each company operates before drawing conclusions about its financial risk.”
nOn the implications for the economy, he said: “For the Nigerian economy, corporate borrowing has both positive and negative implications. Productive borrowing can finance expansion, employment, infrastructure and increased output. But excessive corporate leverage across sectors could increase financial vulnerability, particularly where companies depend heavily on foreign-currency borrowing or face weak consumer demand and high financing costs.”
nMeanwhile, Egbomeade noted that the debt-to-equity ratio is an important measure of financial leverage because it indicates the extent to which a company is financing its operations with debt compared with shareholders’ funds.
nA ratio of 1.0 indicates debt equivalent to equity, while a ratio of 2.0 means debt is twice the reported equity. However, there is no universal debt-to-equity ratio that can be described as appropriate for every company.
nCapital-intensive businesses may naturally require greater borrowing than companies with less capital-intensive operations. Banks, mortgage institutions, telecommunications companies and manufacturers, for instance, may have very different balance-sheet structures.
nConsequently, investors need to examine the ratio alongside profitability, cash flow, interest expenses, debt maturity, asset quality and the company’s ability to generate sufficient income to service its obligations.
nWider economic implications
nFurthermore, another analyst emphasised the wider economic implications, stressing that the debt position of listed companies also has implications for the Nigerian economy.
nAccording to her, corporate borrowing can support economic growth when funds are channelled into productive investments. Manufacturing expansion can create jobs, telecommunications investment can improve connectivity, while infrastructure-related investments can support productivity across sectors.
nHowever, widespread corporate balance-sheet weakness could have the opposite effect. Companies under excessive debt pressure may cut capital expenditure, reduce employment, dispose of assets or postpone expansion.
nFor the banking system and other lenders, corporate debt levels also matter because companies experiencing repayment difficulties could affect asset quality.
nThe data therefore underscores the importance of strong corporate governance, prudent borrowing and adequate capitalisation.
n nRelated Stories
 General News
CELEBRATING TWO YEARS OF TRANSFORMATIONAL LEADERSHIP IN THE PRESIDENTIAL AMNESTY PROGRAMME
Tomorrow, 14TH March 2026, as we look forward to the second anniversary, we reflect on the remarkable two years since the Administrator of the Preside
 General News
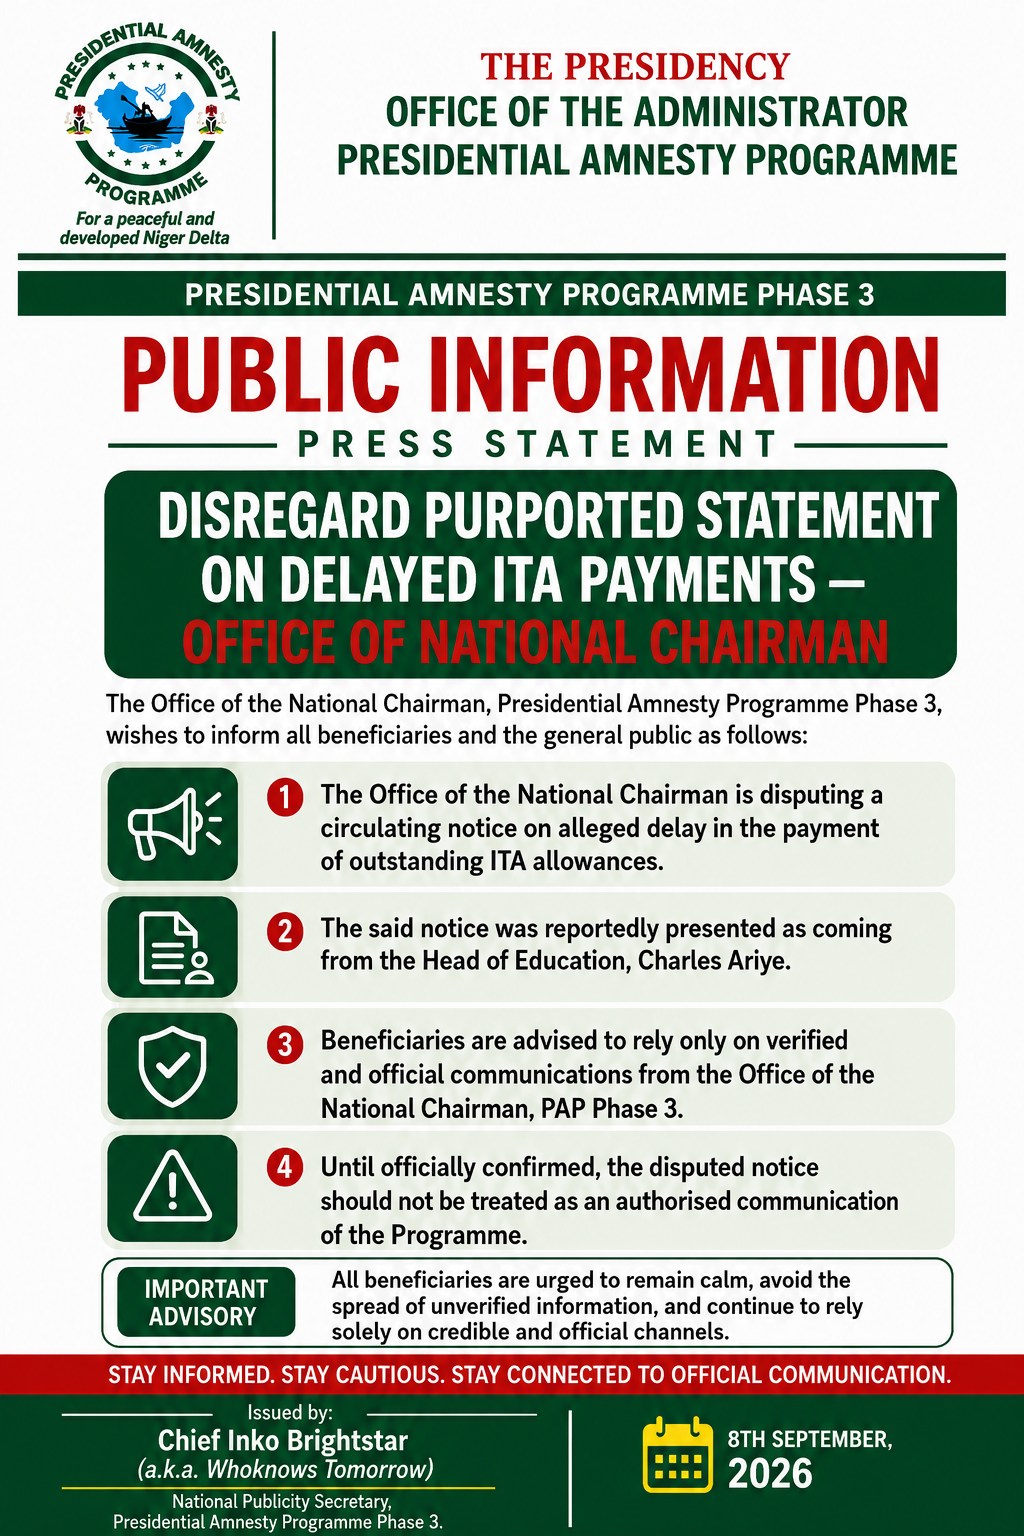
PRESIDENTIAL AMNESTY PROGRAMME PHASE 3: DISREGARD PURPORTED STATEMENT ON DELAYED ITA PAYMENTS — OFFICE OF NATIONAL CHAIRMAN
The Office of the National Chairman of the Presidential Amnesty Programme Phase 3, General Elaye ThankGod Dollar Slaboh, has called on beneficiaries a
 General News
RE: CLARIFICATION ON MY PERSONAL RELATIONSHIPS
PUBLIC NOTICErnrnRE: CLARIFICATION ON MY PERSONAL RELATIONSHIPSrnrnIt has become necessary to make this public clarification following the increasing